The autumn air carries the sharp scent of damp red oak leaves and drying asphalt outside your living room window. Down the street, a backhoe idles, its yellow chassis trembling against the gravel while two workers in mud-caked boots measure the curb cut with a fiberglass tape. From inside your home, the low mechanical purr of the refrigerator feels reassuringly mundane, grounding you in the illusion that your household expenses are entirely within your control.
You open the mailbox, sift through the glossy grocery flyers and unsolicited insurance pitches, and find the plain white envelope bearing the county treasurer’s seal. It looks just like the statement you reviewed last November, but the line items tell an entirely different story. A quiet, five-figure municipal capital bond has slipped onto the ledger, tucked right beneath the routine school district allocation and county road millage.
We are conditioned to think clean drinking water is simply a matter of twisting a brass tap or changing a countertop charcoal cartridge. You imagine federal environmental cleanups are paid for through grand national appropriations passed under the glowing chandeliers of the Capitol. But when regulatory agency timetables collide with hundred-year-old subterranean infrastructure, the financial bill does not evaporate into Washington’s balance sheets. It travels straight down through cold, dark utility easements until it settles square on your doorstep.
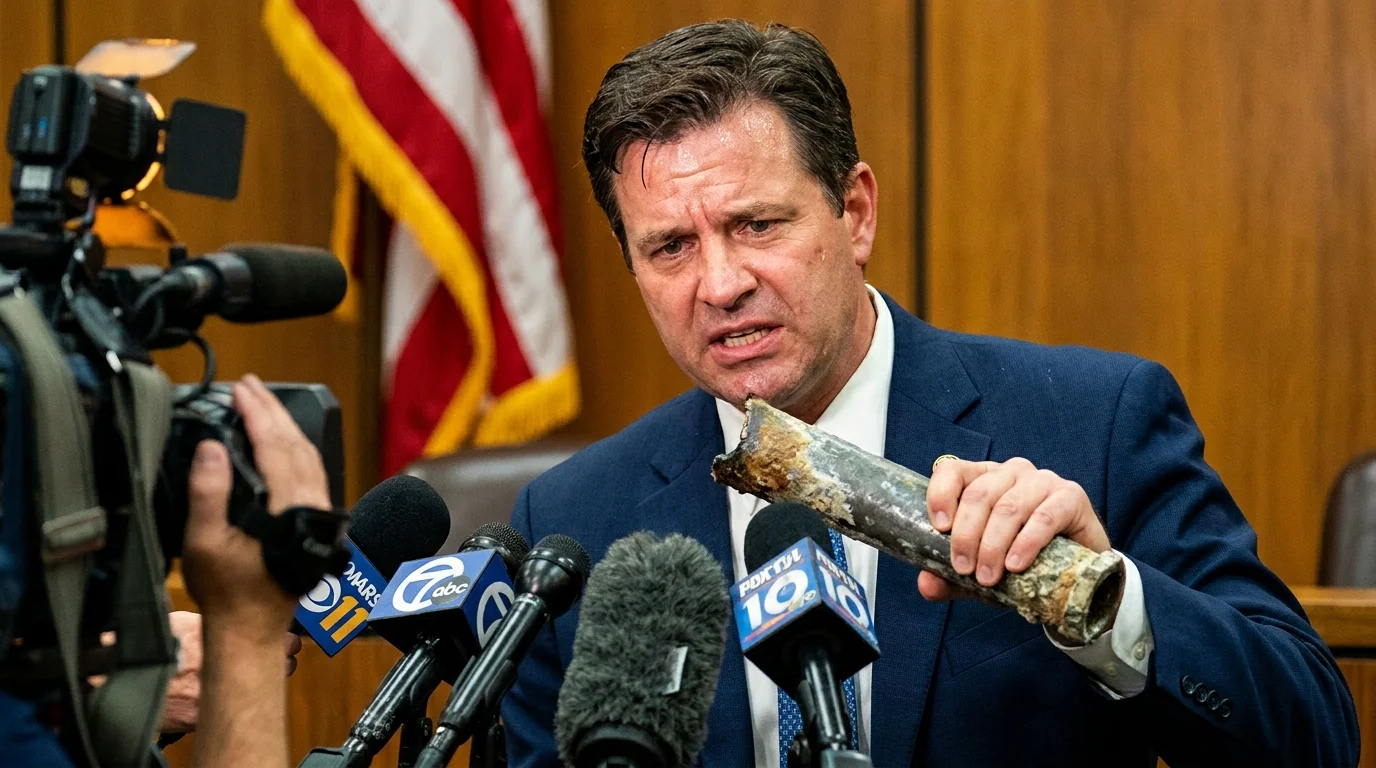
Behind the righteous moral victory of removing toxic lead conduits lies an unaddressed fiscal collision. The heavy mechanical cost of digging up residential streets is bypassing regional water bill line items and anchoring itself directly to real estate valuations, turning homeowners into unwilling underwriters for overdue civil engineering.
The Phantom Plumbing Debt Behind Your Annual Property Levy
To grasp why your real estate taxes are climbing, you have to stop viewing the water utility as an isolated subscription service like electricity or home internet. Think of your municipal budget instead like a shared community roof that began leaking three decades ago, while elected officials merely repainted the drywall to mask the rot. When a strict federal edict arrives requiring total replacement of subterranean lead feeds within a tight ten-year window, there is no magic vault of surplus cash waiting beneath city hall.
Water authorities face hard statutory limits on how rapidly they can spike volumetric water rates without triggering mass utility non-payment or administrative rate protests. General obligation bond issuances become the fastest escape hatch for city managers under federal consent decrees. Instead of charging you an extra twenty cents per gallon consumed, the county pledges its broad taxing power to service forty-year municipal debt packages, guaranteeing investors that property owners will cover the debt service regardless of water usage.
- Turnout propensity weighting models derail working-class voter forecasts until election night precinct totals
- John Fetterman floor demands force high-stakes Senate showdown over domestic steel manufacturing permits
- James Talarico debate clashes trigger fierce floor arguments over private school voucher funds
- Michigan primary ballots shift national race momentum through early union worker turnout
- House Armed Services markups switch contested procurement language during closed midnight sessions
This is the classic unfunded mandate shift: the federal standard commands the remediation, the state agency monitors compliance under threat of statutory fines, but the financing burden slides down the institutional ladder until it hits the municipal ledger. You are no longer just paying for the gallons running through your garden hose; you are paying property tax assessments calculated on the speculative future cost of tearing up every neighborhood curb between your driveway and the municipal reservoir.
For Marcus Vance, a 52-year-old county budget analyst in eastern Pennsylvania, this balance-sheet migration is an everyday reality rather than an abstract economic theory. Marcus spent his late summer evenings in a windowless municipal annex cross-referencing street-level service line inventories against twenty-year debt repayment schedules. He watched as his commissioners realized that their initial federal infrastructure grants would cover less than thirty percent of the replacement costs across three historic boroughs. To prevent an immediate downgrading of the township’s credit rating, they rolled the remaining eighteen million dollars into a debt service levy, quietly redistributing the balance across two thousand residential tax parcels.
Adjustment Layers: How the Mandate Fractures Different Neighborhoods
The practical fallout of this municipal borrowing does not hit every street with the same force. Depending on where your home sits along the historical development timeline, the compliance burden alters your household finances through different structural mechanisms.
For the Older Core Homeowner
If your house was framed before 1950, you are standing directly at ground zero of both the physical disruption and the tax fallout. Your street likely contains private-side lead service connections running from the curb stop valve into your foundation. When the county issues capital improvement bonds, you pay twice: once through the broad property assessment spike that funds public-right-of-way excavations, and again through mandatory private-side replacement notices requiring out-of-pocket plumber fees or special localized assessment liens pinned specifically to your deed.
For the Newer Subdivision Resident
You might assume that living in a home built in 2004 with copper and cross-linked polyethylene lines insulates you from municipal water debt. It does not. Countywide capital bonding absorbs costs by spreading millage adjustments across all taxable property values within the jurisdiction, not just the homes receiving new pipes. You find yourself paying an extra three hundred to six hundred dollars annually on your escrow statement to finance trenching operations in neighborhoods miles away, subsidizing legacy industrial infrastructure while your own utility bills creep upward to cover system-wide administrative compliance.
For the Fixed-Income Senior
Escrow account adjustments do not care about stagnant retirement portfolios. For retirees living on defined pensions or Social Security, sudden four-figure property tax surges linked to debt service millage can break home stability entirely. Because bond obligations hold legal priority over ordinary municipal services, tax offices cannot easily grant localized waivers for water infrastructure debt, forcing older residents to trim grocery budgets or delay home maintenance just to clear quarterly property levies.
A Tactical Audit of Your Next Tax Notice
You cannot stop federal mandates or municipal bond issuances single-handedly, but you can decode how these infrastructure debts hide in your paperwork before your mortgage escrow falls into an unexpected deficit. Protecting your household budget requires checking the numbers with the same careful eye you would use to inspect a foundation wall.
- Request your county’s Detailed Millage Schedule directly from the local tax assessment website rather than relying on your simplified mortgage servicer statement.
- Look specifically for new line items labeled Debt Service, Water Authority Capital Sinking Fund, or Special Infrastructure Assessment.
- Attend your municipal council’s annual budget hearings in October and November when general obligation debt resolutions are read into the public record.
- Verify whether your municipality requires private-side line replacement disclosure during home sales, which could trap your equity during future buyer negotiations.
Pull out your property records and run a targeted audit. Check the specific bond maturity date listed in your county budget report—most lead remediation bonds run for twenty or thirty years. Calculate your effective millage increase by dividing the dedicated infrastructure assessment by your home’s assessed value, then multiply that against your monthly mortgage impound to project how much your escrow reserve must grow by year’s end.
The Clarity of an Honest Ledger
When you look down at the exposed earth of a utility trench cut into your street, the raw dirt and gravel remind you of the hidden systems keeping everyday life intact. Removing neurotoxins from community water networks is an indisputable public health necessity, but pretending that federal decrees come free of charge only blindsides the families expected to keep roofs over their heads.
Understanding that these infrastructure projects show up on property deeds rather than utility meters strips away the pleasant political illusions. It gives you back your clarity. Knowledge turns an alarming tax spike into an accountable civic balance sheet, giving you the leverage to question how local officials issue bond debt, demand fair distribution across municipal lines, and plan your family’s financial future with eyes wide open.
The true cost of public clean water is never written into the press release; it is etched quietly into the real estate deed.
| Key Point | Detail | Added Value for the Reader |
|---|---|---|
| Bond Financing Shift | Counties issue general obligation bonds to meet federal pipe replacement deadlines. | Explains why property taxes climb even when water consumption drops. |
| Broad Base Taxation | Infrastructure debt is levied across all county parcels, including modern builds. | Shows why newer homes still subsidize older municipal line replacements. |
| Escrow Deficit Traps | Mortgage servicers adjust impound accounts months after county millage hikes pass. | Helps homeowners anticipate sudden four-figure escrow catch-up charges. |
Frequently Addressed Concerns
Why didn’t federal infrastructure legislation fully cover these pipe replacements?
Federal allocations through clean water state revolving funds provide critical seed money, but the total nationwide cost of replacing millions of lead service lines runs into tens of billions. The federal funding covers only a fraction of the actual excavation, labor, and private-property connection expenses, leaving local municipal bonds to bridge the immense financial shortfall.Can I contest the debt service line item on my property tax bill?
You generally cannot contest specific debt service millages approved by local legislative bodies or public ballot referendums. However, you can verify that your property assessment ratio is accurate, ensuring you are not paying an inflated percentage of the county’s total bond obligation relative to your actual market valuation.Is the water company responsible for the pipe under my front yard?
In many jurisdictions, the utility owns only the public service line running from the street main to the curb stop valve at your property line. The remaining pipe connecting the curb stop to your basement meter is often legally private property, meaning local ordinances may mandate that homeowners pay for that segment directly or through special property tax liens.How long will this infrastructure surcharge remain on our tax assessments?
Because most water remediation projects are financed through twenty- or thirty-year municipal bonds, these dedicated debt service millages remain locked onto local property records until the principal and interest are fully amortized, meaning they will affect tax statements for decades to come.Will these municipal line replacements increase my home’s resale value?
While certified lead-free plumbing removes a significant inspection hurdle during real estate transactions, it rarely produces a direct market price premium. Instead, elevated county property taxes resulting from municipal debt can slightly suppress buyer borrowing power by raising recurring monthly housing carrying costs.