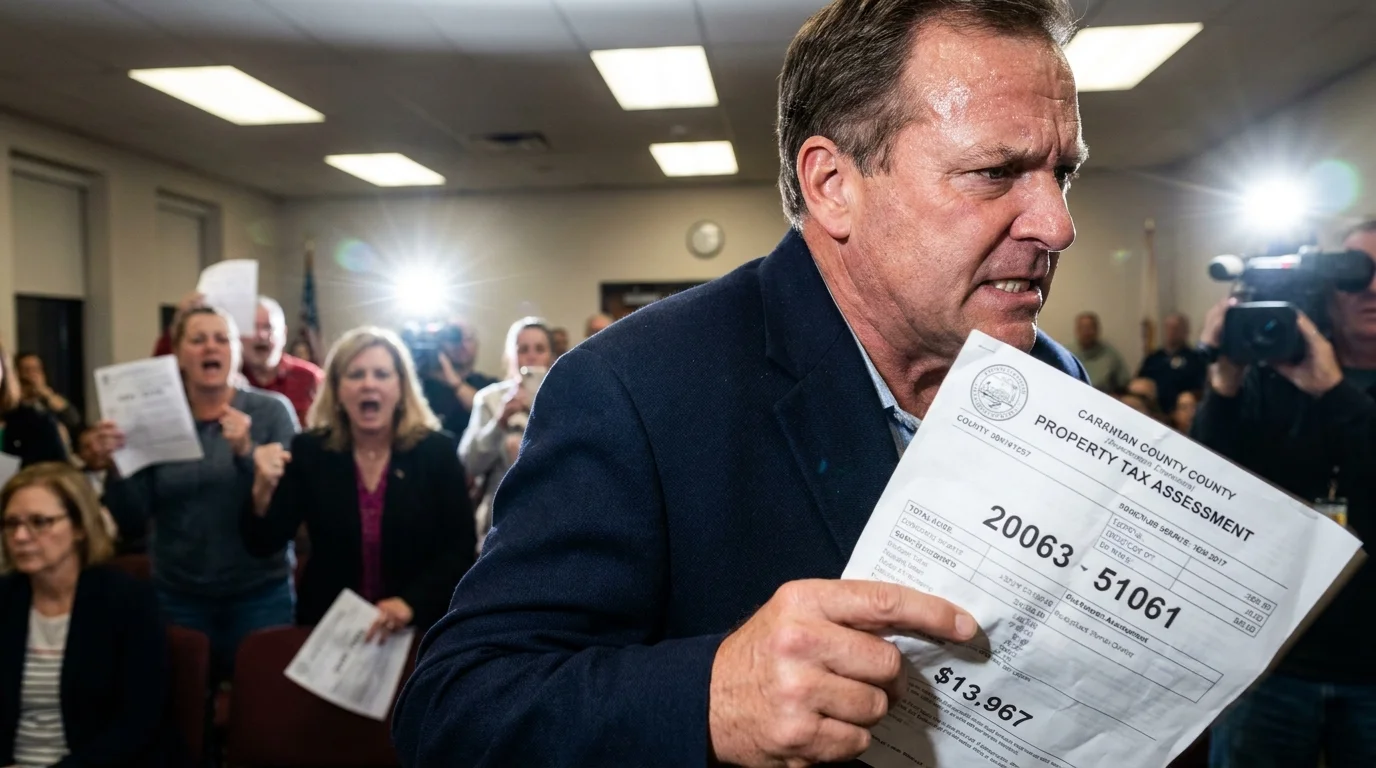
The harsh fluorescent lighting inside the Mineola hearing room hums with a flat, electric buzz that sets teeth on edge. Outside, the damp November chill clings to rows of parked station wagons and sedans lining Franklin Avenue, while inside, the air smells of wet wool overcoats, stale deli coffee, and cheap printer toner. You clutch a cream-colored manila folder stuffed with pink assessment notices, utility slips, and mortgage escrow adjustment warnings that arrived without warning three weeks ago.
A clerk calls the next docket number through a squealing public address system. The room does not step forward; instead, a collective scrape of folding metal chairs reverberates off cinderblock walls as four dozen neighbors push up from their seats at once. For decades, suburban county politics followed an unwritten compact: you accepted the quiet friction of local politics so long as your home remained an untouched sanctuary of predictable school runs, trimmed lawns, and steady equity.
That tranquil certainty dissolved the moment the county’s automated assessment engine reran its residential algorithms. What was promised as an equitable modernization of Nassau’s fractured tax rolls landed on kitchen counters as an immediate, four-figure monthly shock. When the gavels drop, the room refuses to listen, turning its back on the dais in an abrupt wave of fury that leaves party committee members staring at empty folding chairs.
The Assessment Algorithm as a Backyard Fault Line
To grasp why these municipal rooms are emptying out in open defiance, you have to look past the political theater and examine the invisible architecture of municipal appraisal. For nearly two decades, Nassau County operated on a frozen assessment system that papered over discrepancies between rapidly appreciating south shore hamlets and historic north shore estates through an opaque web of tax grievances. The system was broken, but it was predictably broken; homeowners paid private grievance firms a percentage of their yearly savings to knock down inflated numbers.
When administrators flipped the switch on a synchronized, countywide reassessment model, they assumed property owners would welcome statistical fairness. Instead, the mathematical overhaul functioned like cold water poured over a hot glass dish. By attempting to compress fifteen years of quiet market shifts into a single fiscal cycle, the county inadvertently shifted millions of dollars in school and municipal operational levies onto middle-tier suburban enclaves that previously served as reliable voting bastions.
Arthur Pendelton, a 58-year-old water authority engineer from East Meadow, spent three decades casting a straight party ticket for the very township supervisors who oversaw the reassessment rollout. Standing outside the administrative annex after the mass walkout, his folder flutters in the coastal wind, showing an overnight $4,200 annual assessment bump on a modest split-level ranch. “We built our entire retirement runway on the promise of predictable millage rates,” he explains, tapping a finger against the county’s computer-printed valuation summary. “When you drop an extra mortgage payment into someone’s mailbox in October, party loyalty doesn’t just fray—it vanishes by breakfast.”
- Utah postal worker ballot rumors expose foreign bot networks inflating voter fraud claims
- Eric Adams defense strategies switch public messaging to counter federal bribery allegations
- Supreme Court homelessness rulings upend local shelter funding across western cities
- Vanguard ESG fund policies spark fierce state treasurer boycotts over public investments
- Schedule F reclassifications strip career civil servants of historic federal employment protections
The Anatomy of Broken Precinct Alliances
This localized mutiny is not playing out along predictable national party lines; it cuts directly across historic precinct boundaries, carving natural alliances into bitter rival factions. Understanding your own risk requires seeing which camp your neighborhood falls into under the adjusted ratios.
The Long-Term Equity Anchors: These are the homeowners who have occupied post-war developments for twenty-five to forty years. Their primary asset is paid-off home value, yet their fixed retirement incomes cannot absorb sudden millage recalculations. In precincts across Merrick, Garden City, and Bethpage, these voters are actively organizing independent write-in blocks, abandoning party machines they funded for generations.
The Recent High-Basis Entrants: Commuters who bought homes between 2020 and 2023 at peak market rates and historic interest rate lows now face a secondary squeeze. Because their base assessment reflects transaction highs rather than countywide median averages, their escrow accounts are facing immediate deficits, forcing loan servicers to demand sudden lump-sum cash adjustments to keep mortgages compliant.
The Commercial Cushion Deficit: In districts where retail storefronts and office parks successfully challenged their own valuations through tax certiorari proceedings, the commercial tax base hollowed out quietly. The county’s automated algorithm solved that municipal ledger shortfall not by slashing district spending, but by redistributing the uncollected freight onto suburban driveways.
Mindful Steps to Challenge Your Notice
Tossing an assessment notice aside out of disgust guarantees you absorb the full blow of the county’s algorithmic estimate. Contesting these adjustments requires surgical precision, not emotional outrage at the hearing microphone. The objective is to dismantle the county’s comp selection using raw physical data.
- Pull your home’s official property card from the Department of Assessment portal and verify interior square footage, unheated basement classifications, and bathroom counts.
- Isolate three comparable sales within your immediate school district boundary that closed within six months of the appraisal baseline, ignoring homes across major parkways or municipal borders.
- Document deferred structural maintenance—including deteriorating roof decking, unrenovated electrical panels, or foundational settling—with time-stamped photographs to defeat pristine neighborhood comps.
- File a formal appeal with the Assessment Review Commission prior to the statutory deadline, bypassing high-fee grievance mills that take half your first-year relief.
Keep your technical filing concise: municipal hearing officers review hundreds of dockets an hour and respond to hard spatial discrepancies rather than general complaints about local government spending.
The Realignment of Suburban Leverage
The fury boiling through Mineola hearing rooms signals something far deeper than temporary homeowner irritation: it marks the quiet death of inherited suburban voting habits. For over half a century, county leadership counted on affluent, manicured enclaves to rubber-stamp infrastructure bonds and local leadership out of generational routine. That domestic compliance was always predicated on an unspoken deal: insulate the backyard from fiscal volatility.
Now that the veil of algorithmic neutrality has fallen, residents are discovering that hyper-local administrative rules matter far more to their daily lives than cable news theatrics. A single shifted decimal place in a county basement office holds the power to decide whether an aging parent can afford to age in place or whether a young family must list their house by spring. By stepping out of those hearing rooms and onto Franklin Avenue, suburban homeowners are not surrendering—they are learning how to wield their geographic veto.
The moment a local government treats a family home as a ledger calculation rather than a community root, political loyalties dissolve overnight.
| Adjustment Trigger | Administrative Mechanism | Actionable Taxpayer Response |
|---|---|---|
| Algorithmic Comp Spike | Automated valuation models pulling high-value neighborhood outliers to set baseline medians. | Audit property card dimensions; contest square-footage calculations with recorded surveys. |
| Commercial Burden Shift | Corporate tax certiorari settlements transferring levy burdens onto residential classes. | Cross-examine school district apportionment ratios during open municipal budget workshops. |
| Escrow Impound Cascade | Mortgage servicers recalculating monthly escrow payments to cover projected tax shortages. | Submit certified copy of active grievance filing to mortgage servicer to pause supplemental debits. |
Frequently Asked Questions
Will walking out of a county assessment hearing dismiss my tax bill?
No. A public walkout sends a political warning to county executives, but administrative appraisal notices stand as legally binding unless challenged through an official appeal with the county Assessment Review Commission.Why did my assessment spike if my home has not been renovated in years?
The county’s reassessment model relies on neighborhood sales comps and predictive market algorithms rather than interior inspections, meaning surrounding home sales directly inflate your baseline value regardless of your interior condition.Does filing a formal property tax grievance trigger an in-person home inspection?
Under New York state and Nassau County procedures, filing a grievance does not automatically grant county appraisers the right to enter your home; appeals are predominantly decided on exterior assessments and submitted documentation.How quickly does an assessment hike hit my monthly mortgage payment?
Servicers typically perform annual escrow analyses between November and February; if an adjusted tax rate creates an escrow shortage, your monthly mortgage payment will increase within 30 to 60 days of their recalculation.Can school districts lower their tax rates to offset the county’s higher assessments?
School boards set levy requirements based on their approved operating budgets; while they can technically adjust millage rates, most maintain their targets, allowing reassessment spikes to flow directly onto tax bills.