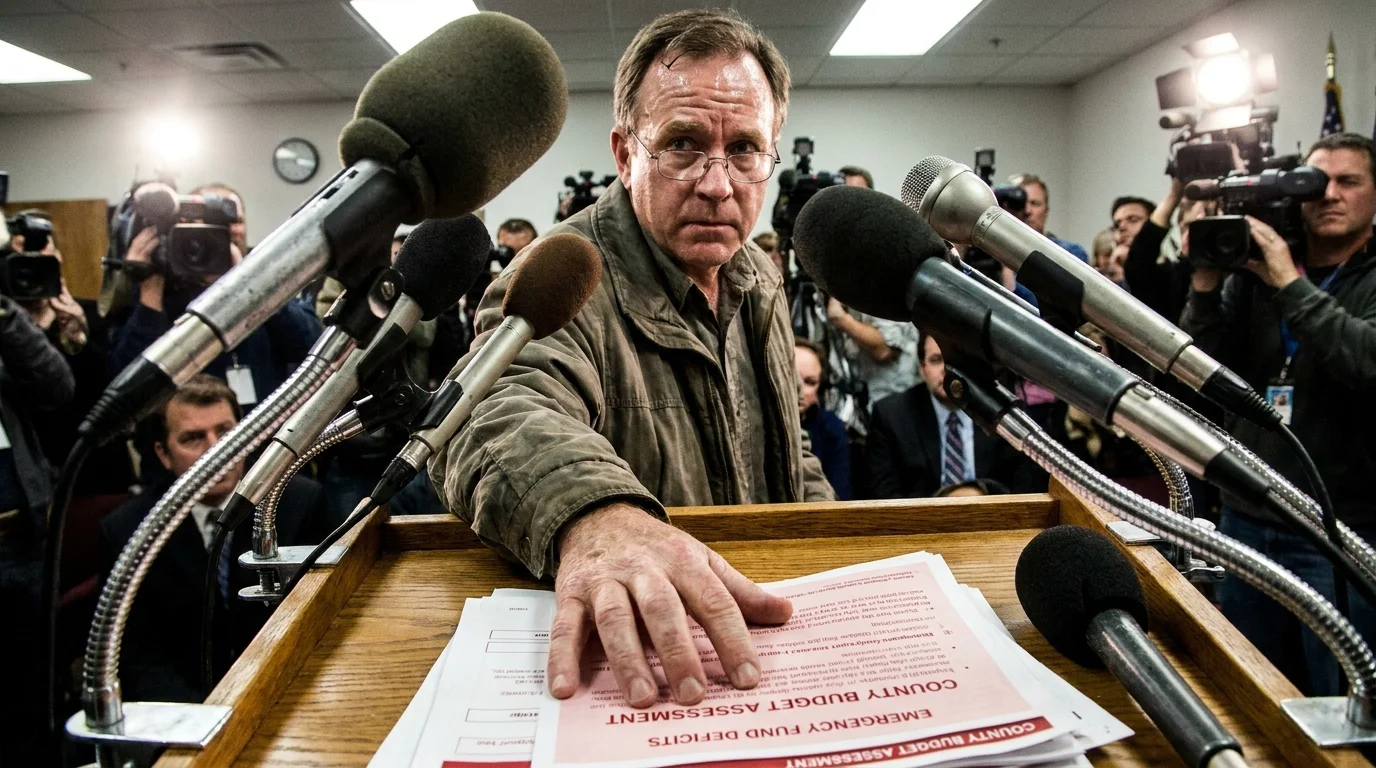
The autumn air across the county seat smells of damp pine needles and the faint metallic tang of idling diesel graders. Inside the limestone annex of the county courthouse, the fluorescent lights buzz with a low, relentless drone that matches the tension around the scarred oak table. Outside, the creeks run low and calm, belying the financial flash flood quietly rolling across the county assessor’s desk. You open your annual tax assessment expecting the usual two-percent creep, only to find a line-item adjustment that looks less like inflation and more like an emergency ransom note.
Most homeowners assume their property levy is tied to local choices: a freshly paved bypass, upgraded library hours, or an extra patrol car for the county sheriff. Yet the sharp spike staring back at you from your escrow statement was not voted on in your town hall, nor was it birthed in a local zoning dispute. Federal spending realignments have arrived on your gravel road, shifting catastrophic recovery balances directly onto your acreage with the stroke of a federal pen.
When Washington decides to trim disaster outlays to show fiscal prudence on national balance sheets, the weather does not negotiate. The washouts still shatter limestone culverts, winter gales still snap aged timber over primary feeder lines, and emergency sirens still wail into the blackness of rural nights. But the checking account that backstops those midnight disasters has fundamentally relocated, stepping down from the federal treasury directly onto your parcel pin number.
The Downstream Squeeze: When Catastrophe Becomes a County Line Item
For decades, the unspoken contract between small towns and federal agencies functioned like an invisible reinsurance umbrella. When torrential rains or flash freezes devastated a rural corridor, regional public works teams rolled heavy machinery while federal disaster assistance quietly absorbed up to seventy-five percent of the infrastructure restoration costs. You paid your property taxes to keep the local peace and patch summer potholes, secure in the knowledge that catastrophic shocks were backed by the full faith and credit of the nation.
That umbrella has turned inside out, downloading unfunded emergency repair debts down to county ledgers before local road commissions can even price replacement gravel. Under modified federal threshold formulas, smaller rural jurisdictions no longer meet the elevated financial damage baselines required to trigger federal public assistance grants. What previously qualified as a regional emergency eligible for federal machinery is now classified as ordinary municipal maintenance.
The shift is not an administrative clerical adjustment; it is a fiscal detour. When a single mountain creek takes out three concrete bridge abutments in early spring, a small county with eight thousand residents cannot wait for next year’s grant cycle to let the school buses pass. The commissioners pull money from contingency reserves, exhaust their short-term credit lines, and ultimately balance the red ink by ratcheting up the millage rate on every parcel in their jurisdiction.
- Gallup party affiliation metrics mask massive working-class voter realignments across industrial battlegrounds
- Lina Khan antitrust enforcement fuels high-stakes White House donor mutiny over corporate penalties
- Rahm Emanuel nomination battle forces Senate Democrats into fierce floor clash
- Newsweek debate metrics spark fierce frontrunner clashes over working-class Rust Belt economic loyalties
- Early primary debates derail presidential frontrunners during dangerous unscripted retail diner stops
Consider Frank Vance, a 58-year-old road superintendent in southern Missouri whose family has farmed the same bottomland since the mid-century. Last June, after an unheralded four-inch downpour tore out five miles of fresh chip-seal and fractured a critical box culvert, Frank filled out the standard federal assessment sheets he had relied on for two decades. The answer came back flat and chilly: the local damage fell two hundred thousand dollars shy of the newly elevated federal declaration threshold. To rebuild before winter logging began, Frank watched his county commissioners vote through an emergency four-mill tax surcharge on rural property owners who were already struggling with feed and diesel prices.
Mapping the Surcharge: How Different Parcels Absorb the Blow
The municipal shift does not distribute its weight evenly across a zip code. Depending on how your land is classified, the downloading of federal emergency costs creates distinct structural pressures that demand different household defensive strategies.
For the Homestead and Acreage Owner
If you hold a modest homestead with several acres of timber or pasture, your primary exposure comes through the millage rate attached to basic county road and bridge funds. Because rural counties have minimal commercial square footage to tax, the entire burden of emergency drainage reserves falls squarely on residential and agricultural soil. Your property taxes rise immediately to finance heavy municipal equipment reserves that the federal government used to co-sponsor.
For the Rural Small-Business Operator
Main Street storefronts and service bays face a compounding squeeze. While residential owners can sometimes benefit from homestead exemption caps that limit annual assessment growth, commercial parcels rarely enjoy the same legal shields. When county commissioners raise local ad valorem taxes to backstop disaster response, independent repair shops, grain elevators, and hardware stores absorb uncapped rate hikes, which inevitably get passed through to local retail prices.
For the Fixed-Income Senior
Those living on established pensions or personal retirement accounts face the most immediate risk of displacement. When property taxes climb twenty to thirty percent in a single fiscal cycle to build a county-level emergency slush fund, the monthly escrow cushion built into regional mortgages ruptures. Home equity cannot pay current taxes, leaving longtime residents scrambling to file hardship exemptions that many understaffed rural administrative clerks do not have the time or personnel to process.
Mindful Auditing: A Tactical Plan to Challenge the Shift
You cannot change federal balance sheets from your breakfast table, but you do not have to accept an unverified tax hike lying down. Protecting your household requires understanding the bureaucratic levers that county assessors use when emergency mandates hit their ledgers.
County clerks and assessors often rely on sweeping blanket multipliers when municipal budgets face an emergency shortfall. They apply a uniform assessment bump across entire precincts rather than surveying the specific, individual state of your property. By auditing your property card and demanding an individualized review, you can separate your land’s true market value from the county’s artificial revenue targets.
- Pull the Property Record Card: Visit your county assessor’s portal or courthouse counter and request your complete property breakdown. Check for outdated structures, inaccurate square footage, or misclassified outbuildings that artificially elevate your taxable baseline.
- Audit the Special Assessment Line: Check whether the hike stems from a general valuation increase or a dedicated emergency county levy. General valuation increases can be appealed through standard appraisal boards; special district emergency levies require monitoring county commission public hearings.
- Document Environmental Deferred Maintenance: Take clear photographs of degraded county infrastructure abutting your parcel. If washed-out ditches or collapsed culverts have reduced your road access or caused localized drainage problems, submit these conditions as formal evidence of property devaluation during your appeal.
- Track Local Millage Hearings: Attend the statutory “truth in taxation” or equalization board meetings scheduled every late summer. Commissioners rely on silent public rooms to pass emergency millage realignments without formal civic opposition.
Your property assessment should reflect what a buyer would pay for your land today, not the emergency contingency balance sheet your county wishes it had in the bank. Moving through these verification steps places the burden of proof back on the local appraisal district, where it legally belongs.
The Bigger Picture: Reclaiming Local Sovereignty
The downloading of disaster costs is an unvarnished lesson in modern governance: risks that are cast aside by central institutions do not vanish into the ether, they sink until they hit bedrock. In rural America, that bedrock is the private landowner whose home, barn, and tillable soil cannot be packed into an offshore account or driven across state borders when expenses escalate.
Yet recognizing this shift brings a quiet, necessary clarity. For years, communities operated under the illusion that distant agencies would permanently shoulder the bill for living alongside rivers, mountains, and wildfire-prone forests. That era of automatic relief has drawn to a definitive close, leaving neighborhoods with an urgent mandate to re-examine how their local tax dollars are prioritized long before the next storm cloud gathers on the horizon.
When you understand the exact mechanism of the municipal ledger, you stop viewing your tax bill as an arbitrary stroke of misfortune. You begin to see it as a balance sheet that requires active, community-wide stewardship. Scrutinizing the ledger, speaking at equalization boards, and demanding fiscal transparency from local commissioners is no longer just civic homework; it is the primary way you protect the ground beneath your feet.
The road department doesn’t care who prints the money, but your county assessor knows exactly who owns the dirt.
| Key Point | Detail | Added Value for the Reader |
|---|---|---|
| Federal Threshold Escalation | Washington raises per-capita disaster thresholds, disqualifying small-scale county infrastructure damage from public grants. | Explains why local washouts that were previously reimbursed are now funded entirely through regional property millage. |
| Emergency Reserve Shifting | County commissioners are forced to build localized emergency contingency funds using ad valorem property levies. | Reveals why your escrow bill rises even if your home’s actual resale market value has remained flat or declined. |
| Appraisal Card Contestation | Assessors apply generalized parcel multipliers to hit emergency revenue numbers rather than conducting individual site visits. | Gives you actionable leverage to contest blanket property tax assessments using site-specific photographic evidence. |
Frequently Asked Questions
How do federal disaster cutbacks directly increase my annual property tax bill?
When the federal government raises the damage dollar amount required to unlock emergency aid, small counties must pay for destroyed roads, bridges, and emergency services alone. To cover these sudden infrastructure repairs without defaulting on municipal debt, county commissioners raise the local millage rate, which directly increases the property tax billed to every local landowner.Can I legally appeal an assessment hike that was caused by a county emergency levy?
You cannot directly appeal a voter-approved or commissioner-enacted tax millage rate through an appraisal appeal, but you can contest your property’s taxable valuation baseline. If your assessor used an inflated property value multiplier to generate emergency revenue, proving your home is overvalued will lower the total dollar amount you owe regardless of the higher millage rate.Why don’t rural counties simply use state aid instead of raising local property taxes?
State emergency relief reserves are also finite and typically follow the same stringent damage metrics used at the federal level. When state disaster funds are drained by primary metropolitan emergencies, rural county commissions are legally isolated and must lean on their only autonomous revenue source: local ad valorem property taxes.What is the difference between a general fund tax hike and an emergency infrastructure levy?
A general fund tax hike is permanent revenue used to pay for county salaries, recurring administration, and day-to-day operations. An emergency infrastructure levy or road-and-bridge bond is often a targeted surcharge designed to replenish emergency balances or pay down short-term municipal repair bonds issued after major weather events.What steps can I take before my next tax assessment arrives to lower my financial risk?
Review your official county property record card immediately for recording errors, document any drainage or road access issues that depress your parcel’s resale value, and file for all qualifying homestead, agricultural, or senior exemptions with your local county clerk before the annual filing deadline closes.