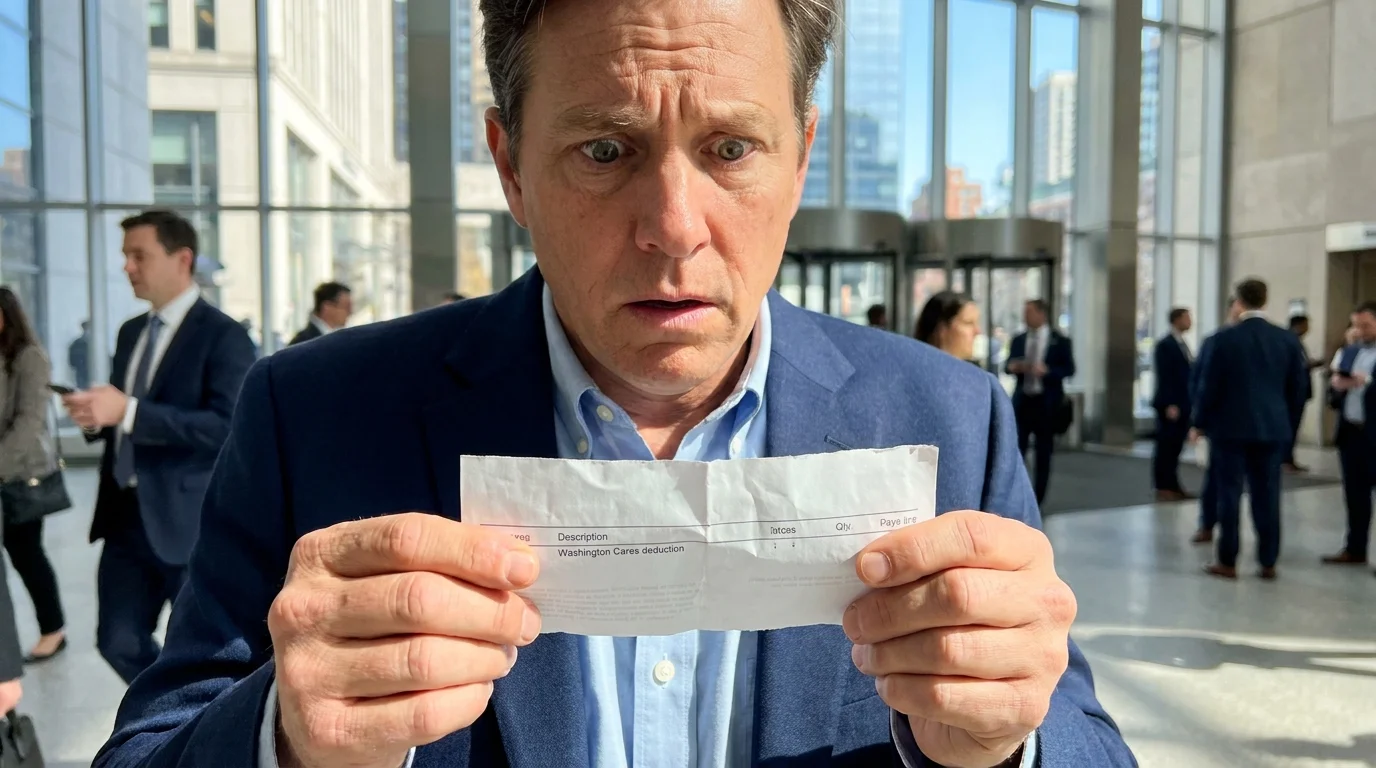
The kitchen is still blue with predawn light when you pull open your mobile banking app. The radiator clicks quietly behind the table, and the coffee in your mug has cooled just enough to drink without scalding your tongue. It is Friday morning, the day your biweekly pay is supposed to land in your checking account like clockwork. You know the exact cadence of your numbers: gross salary, federal withholding, FICA, health insurance premiums, net balance. It is a mental ledger you have kept balanced for years.
Yet today, the balance sitting in bold black font on your screen doesn’t match your calculation. It is lighter by fifty-eight dollars and change. Over the course of twelve months, that quiet shortfall amounts to more than fifteen hundred dollars—the price of a family’s annual auto insurance premium or three months of groceries.
When you log into your employer payroll portal to open the stub, you scan past the familiar deductions. Right beneath Medicare, nestled between voluntary dental coverage and local transit subsidies, sits a crisp new acronym: WA Cares payroll deductions, or LTSS. No human caseworker called you. No individual ballot asked for your signature last November. The line item appeared with the silent finality of an automated script running on a cloud server at midnight.
The Legislative Phantom: Turning State Compromise Into Direct Escrow
To grasp why your take-home pay shriveled before your electronic deposit cleared, you have to look past the political stump speeches and trace the mechanics of statehouse statutory compromise. The program was designed not as an optional safety net you select during open enrollment, but as a mandatory, uncapped payroll assessment. It functions like an unmonitored garden hose with a micro-perforation: you barely hear the hiss, but the pressure drops steadily across your household ledger.
Lawmakers wrestled behind closed doors in Olympia over how to backstop a fragile long-term care Medicaid safety net without levying a direct, politically hazardous income tax. The compromise was an administrative sleight of hand. By framing the deduction as an automatic social insurance premium—strictly fifty-eight cents on every one hundred dollars earned—the policy bypassed constitutional ballot referendums while shifting the entire operational burden directly onto company payroll software.
What makes this deduction unique among state levies is the complete absence of an income ceiling. Unlike Social Security, which caps its taxable wage base once your earnings hit six figures, this mandatory siphon follows every single dollar you generate. If you pull weekend overtime, complete a grueling holiday swing shift, or receive an unexpected annual performance bonus, the deduction takes an expanding bite out of the check before your bank registers the incoming transfer.
- Persian Gulf tanker insurance spikes trigger sudden fuel price jumps at coastal terminals
- Cuban Missile Crisis declassified tapes expose secret military pressure on presidential negotiators
- Donald Trump tariff threats against Canada spark starkly opposing broadcast coverage divides
- Nassau County property tax revaluations trigger furious suburban homeowner walkouts at hearings
- Utah postal worker ballot rumors expose foreign bot networks inflating voter fraud claims
Elena Vance, a 42-year-old logistics supervisor living in Kent, discovered the adjustment the hard way after negotiating a hard-fought five percent merit raise last winter. “I ran the numbers with my partner to figure out if we could absorb our rising property taxes,” Elena told colleagues after auditing her pay advice. “When my raise finally kicked in, nearly twenty percent of the gross increase was immediately swallowed by this single state withholding line. Nobody knocked on my door to explain that my promotion was already earmarked for a state program I might never qualify to use.”
The Three Tiers of Exposure: Who Bears the Weight
The practical fallout of this statutory withholding does not land evenly across the state workforce. Depending on your career trajectory and where your bedroom sits relative to state lines, the mechanical deduction creates three distinct categories of friction.
The Salaried Overachiever: If your income depends on quarterly bonuses, equity vesting, or salaried performance incentives, you experience an accelerating drag on gross earnings. Because there is no statutory limit on assessable income, high-responsibility workers pay exponentially more into the fund while remaining eligible for the exact same fixed lifetime benefit of $36,500, an amount that long-term care actuaries note covers mere months of professional memory care or skilled nursing support.
The Border Commuter: Thousands of workers commute daily across the Columbia River from Oregon or over the state line from Idaho into Washington manufacturing hubs and tech offices. Under the statutory structure, your wages earned inside Washington are automatically docked, yet you are fundamentally barred from ever claiming the benefit unless you relocate your primary residence into the state upon retiring. You fund a community safety net you are legally prohibited from touching.
The Mid-Career Transplant: For professionals moving into the Puget Sound region in their late forties or early fifties, the vesting rules operate like a mathematical mirage. To qualify for program disbursements, statutory rules mandate that you contribute for either three out of the past six years or for a full ten years without a five-year break. If you plan to retire out of state in eight years, every dollar stripped from your biweekly stub remains locked in state coffers forever.
Auditing Your Stub: Mindful Steps to Reclaim Control
You cannot simply opt out at your discretion through human resources anymore. The original window to purchase private commercial insurance and file a permanent state exemption slammed shut in late 2021. However, navigating the statutory mechanics mindfully allows you to pinpoint where your wages are bleeding and determine if statutory exemption clauses apply to your status.
Take twenty minutes this weekend to conduct a thorough payroll audit using this deliberate protocol:
- Pull the raw pay statement: Do not rely on mobile deposit snapshots. Download the full itemized PDF from your payroll provider (such as ADP, Workday, or Paychex) to verify the exact code assigned to the line item.
- Calculate your annual extraction rate: Multiply your gross annual compensation by 0.0058. Divide that total by your annual pay periods (26 for biweekly, 24 for semimonthly) to confirm your employer software is not over-withholding on irregular bonus schedules.
- Review statutory exemption eligibility: If you are a military spouse, an employee holding a non-immigrant temporary work visa (such as an H-1B or L-1), or a documented border resident with a primary domicile outside Washington, file for an ongoing administrative exemption through the state Employment Security Department (ESD) portal immediately.
- Recalibrate your household savings buffer: If you are ineligible for an exemption, adjust your automated transfers to personal savings accounts downward by that exact deducted amount so your checking account does not face unexpected mid-month overdraft exposure.
The Tactical Paycheck Toolkit:
Keep these specific baseline metrics handy when reviewing your compensation records this quarter:
- Statutory Withholding Rate: exactly 0.58% ($0.58 per $100 gross earnings)
- Exemption Portal Authority: Washington Employment Security Department (ESD)
- Standard Vesting Horizon: 10 consecutive years (or 3 of the last 6 years with at least 500 hours annually)
- Maximum Lifetime Benefit Cap: $36,500 (adjusted intermittently for inflation)
The Psychology of the Invisible Cut
There is a distinct psychological difference between writing a physical check to clear a property tax bill and watching your pay quietly diminish before your bank deposits clear. The modern administrative state relies heavily on the friction-free nature of automated clearing houses. When deductions are processed in the quiet background of cloud payroll engines, public frustration is dampened by the sheer banality of the interface.
When you take the time to audit your earnings statement and understand the mechanics behind each withholding line, you reclaim active ownership over your household labor. You transform from a passive recipient of an altered direct deposit into an informed participant who sees the real-world cost of legislative compromise. Understanding where every dollar travels is the only way to budget with absolute clarity in an era of expanding statutory mandates.
The sharpest tax increases never arrive with sirens and parades; they settle into the small print of your earnings statement while you sleep.
| Withholding Metric | Statutory Specification | Added Value for the Reader |
|---|---|---|
| Mandatory Rate | 0.58% across all gross income | Allows you to calculate your exact monthly deficit down to the cent |
| Income Cap | None (completely uncapped) | Helps you project tax drag across overtime, bonuses, and future merit raises |
| Vesting Requirement | 10 years without a 5-year break | Clarifies whether your retirement timeline will render the deduction a total loss |
| Interstate Portability | Zero (benefits forfeit upon out-of-state move) | Informs relocation planning if you intend to leave Washington before old age |
Frequently Asked Questions About Washington Cares Deductions
Can I buy a private long-term care policy today to opt out of the payroll deduction?
No. The statutory deadline to purchase qualifying private commercial coverage and apply for a lifetime permanent exemption expired on November 1, 2021. Any private policy secured after that cutoff cannot be used to escape automatic withholdings.Do Washington Cares payroll deductions apply to independent contractors?
Independent 1099 contractors and self-employed sole proprietors are exempt from mandatory withholdings. However, you can elect to opt into the program voluntarily if you choose to secure coverage.What happens to my withheld money if I move out of Washington state?
Under current state guidelines, workers who permanently move out of Washington forfeit the lifetime benefit, meaning all prior contributions remain within the state trust fund with no cash surrender value or refund available.Why is there no income cap on Washington Cares deductions like Social Security?
The original legislation intentionally removed an earnings ceiling to generate sufficient capital for the trust fund. As a result, higher earners pay significantly more over their careers for the same capped $36,500 benefit.How can cross-border commuters stop Washington Cares withholdings?
If your primary, permanent residence is in another state (such as Oregon or Idaho), you can submit proof of non-residency to the Employment Security Department to secure a conditional exemption from the deduction.